Pay. Send.
Done
A simpler way to pay in stores, online and across eFind — designed around speed, privacy, clear choices and fewer steps.

In stores
Contactless experiences designed to make the amount, merchant and confirmation easy to understand.
Online
A compact checkout designed to reduce repeated forms and card entry at participating merchants.
Send + request
A clear person-to-person flow when supported by the final product and market.
Business
Merchant tools designed around checkout, payment history, refunds and integration clarity.
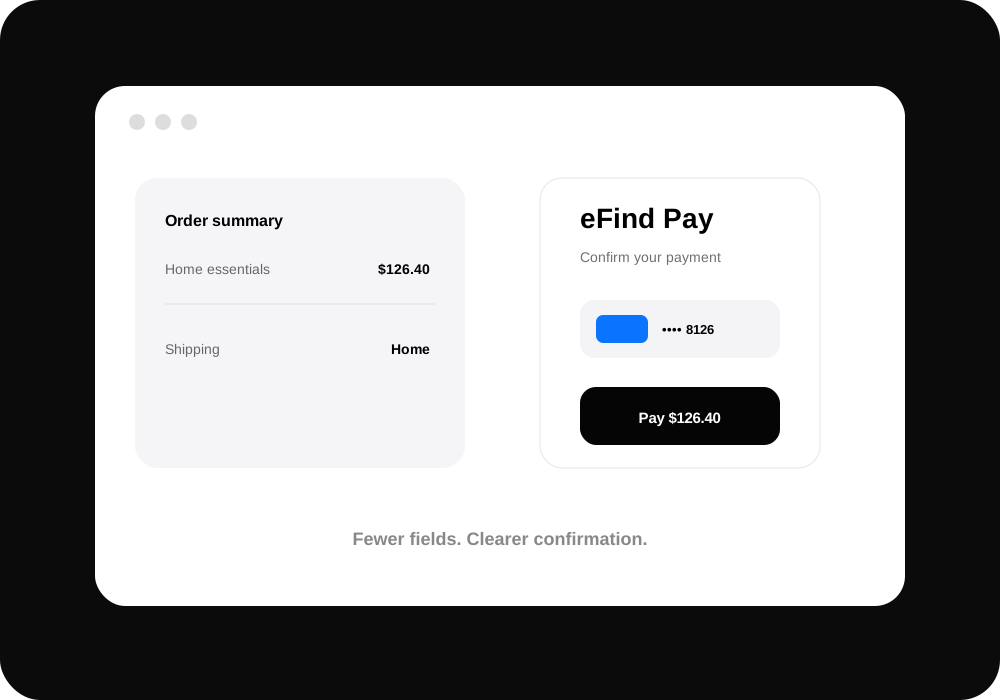
Checkout without the checkout marathon.
The goal is simple: show the merchant, amount, delivery details and payment choice clearly — then let the customer confirm without re-entering information they already saved.
Built for something more valuable than convenience.
Your trust.
Payment products should explain what happens, what information is involved and where to get help. We want those answers to be easy to find.
Protect payment credentials
Production handling, tokenization and merchant data sharing will be documented only after the architecture and partners are confirmed.
Every sensitive action confirms you
Authentication methods will depend on supported devices, identity requirements and market rules.
Controls you can find
Payment methods, activity, privacy choices and support should live in predictable, understandable places.
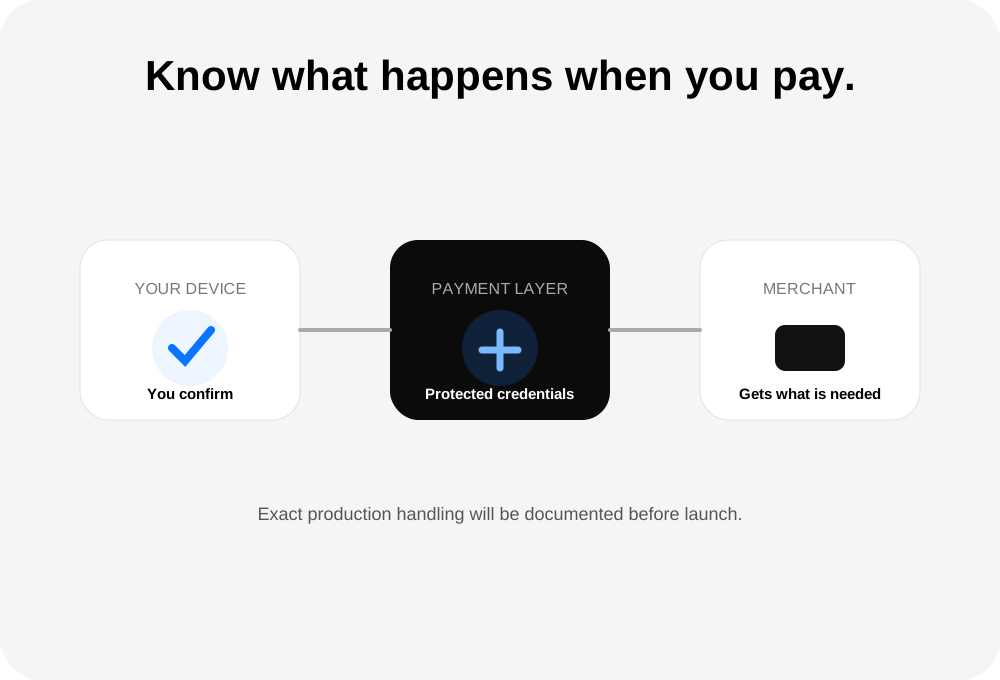
Know what happens when you pay.
Before launch, the Trust Center will document what eFind Pay receives, what participating merchants receive, what partners process, how authentication works, and what information is retained.
We will not use phrases like “bank-grade security” as a substitute for verifiable technical and operational details.
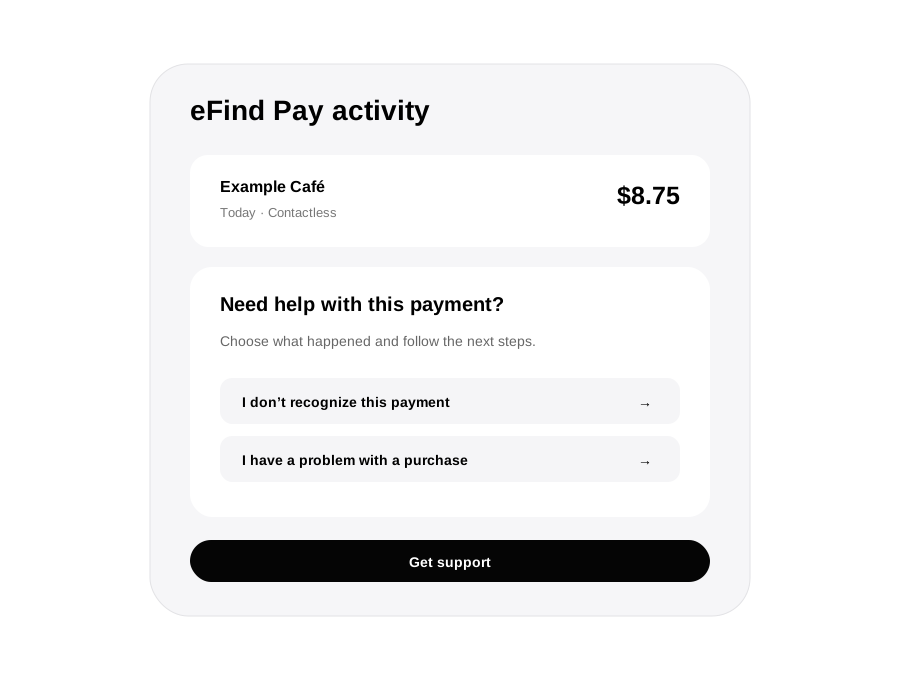
Help should be part of the payment.
The product direction includes a clear path from transaction history to help, so customers do not have to hunt through generic support pages when a payment needs attention.
Payment activity should not become a mystery data trail.
The privacy experience is being designed around clear answers: what information is used, why it is needed, how long it is retained and what choices customers have. Final production practices will be documented before availability.
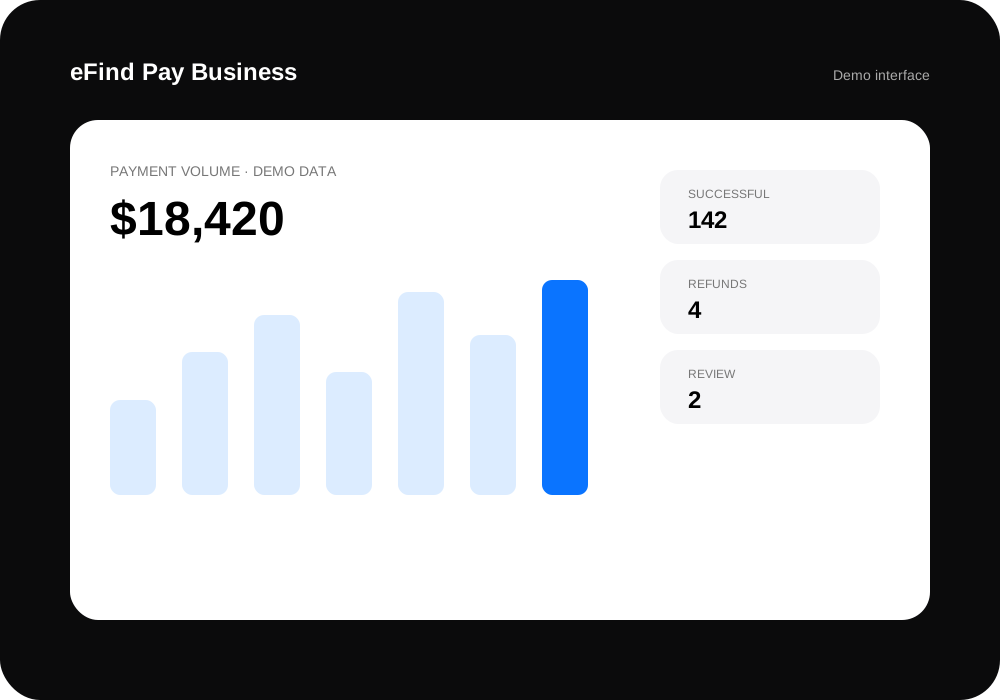
Make the button worth tapping.
For merchants, eFind Pay should be more than another checkout logo. The product direction centers on clear payment states, useful transaction history, refunds, disputes and developer tooling.
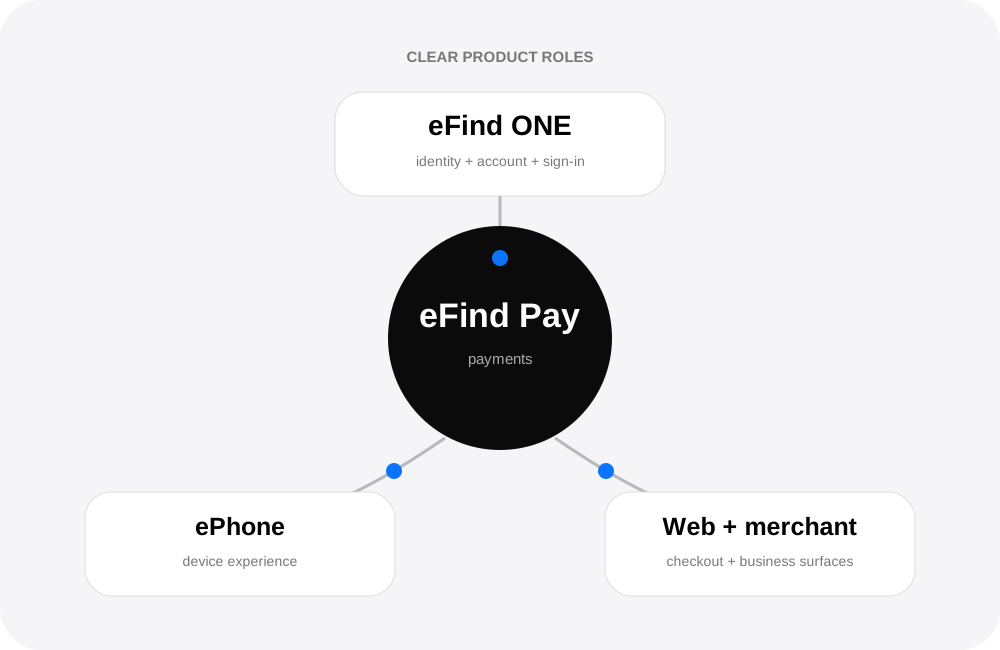
One account. Clear product roles.
eFind ONE remains the identity and single sign-on layer. eFind Pay is the payment experience. ePhone can provide a device experience. Other eFind products remain separate unless a specific connection has a clear purpose and appropriate permission.
The basics, without the fine-print hunt.
Can I use eFind Pay today?
Not yet. This site shows the product direction while eFind Pay is being prepared for launch.
Is eFind Pay the same thing as eFind ONE?
No. eFind ONE is eFind’s identity, account and single sign-on layer. eFind Pay is the payment experience.
Which cards, banks or payment methods will be supported?
Support will depend on the production payment partners and markets. We will publish the verified list before availability.
How will eFind Pay protect payments?
The Trust Center will document the production credential handling, authentication, partner roles, data sharing and retention practices when those details are finalized.
Will eFind Pay charge fees?
Consumer and merchant fees, if any, will be stated clearly before a paid or live payment service is offered.
Follow the build.
Get product updates as eFind Pay moves toward launch readiness.
Joining updates is separate from creating an eFind Pay account. Product availability, partners, fees, supported countries and eligibility will be published before launch.